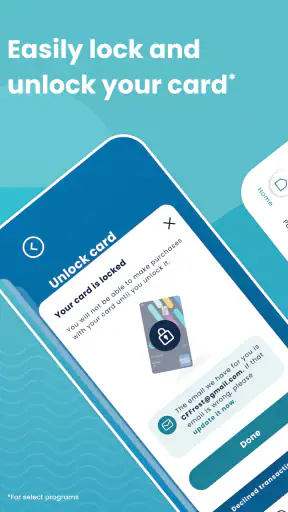
Managing a store-linked credit account is rarely exciting, but it can become surprisingly easy to neglect. I spent time looking at Bread Financial as a daily finance companion, focusing less on the first impression and more on whether it remains useful once the novelty disappears. My view is that it works best as a focused account-management tool: it helps you check what is happening, make a payment, and keep rewards within reach without opening a browser. It is not trying to replace a full banking app, budgeting service, or investment platform, and that narrow purpose is both its main strength and its biggest limitation.
Developed by Bread Financial Holdings, Inc., the free app belongs to the finance category and is available for everyone to use within its stated age rating. It has built a strong audience, with a 4.7 average from around 39 thousand ratings and more than 500 thousand installs. Those figures suggest that many account holders find the basic experience dependable enough to keep around, although popularity alone does not tell me whether it will suit your particular spending habits.
What Bread Financial feels like after the first week
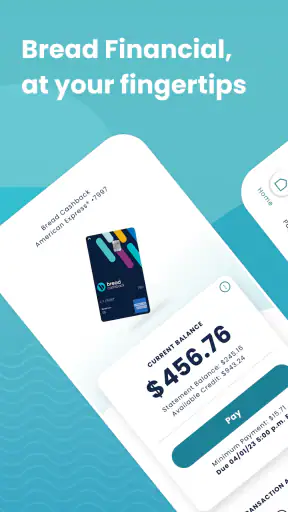
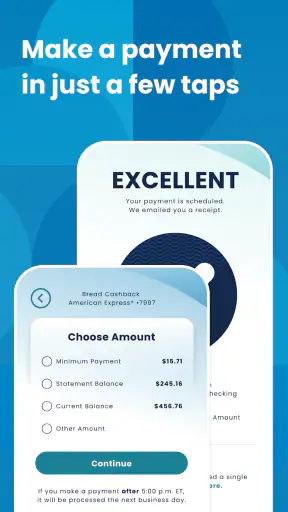
The first-week appeal comes from reducing a small but recurring annoyance: remembering where to manage a Bread Financial account. Instead of treating payments and rewards as separate chores, the app puts them in the same mobile destination. That matters when you are away from a computer, checking an account before making a purchase, or trying to deal with a payment during a busy day.
I like the idea of opening a finance app with a specific task in mind rather than wandering through a large banking dashboard. If your relationship with Bread Financial is limited to one account, a focused interface can feel calmer than a traditional bank application filled with checking, savings, transfers, cards, offers, and unrelated services. The short route from account review to payment is the product’s most convincing everyday benefit.
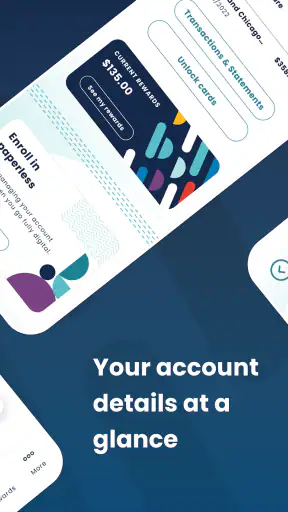
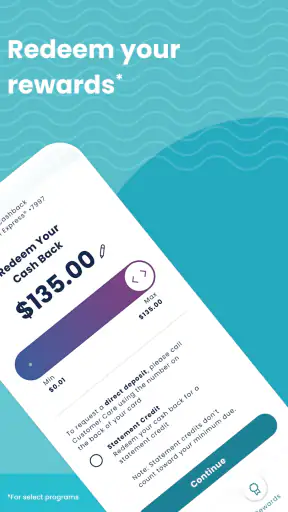
The app also makes rewards more visible than they might be in a paper statement or a browser session. That visibility can change behavior in a useful way. I am more likely to remember a benefit when it appears alongside the account I already check, rather than when it is hidden behind a separate rewards page that I rarely visit. The important distinction is that the app supports awareness and action; it does not automatically make rewards valuable if the underlying redemption choices do not fit your needs.
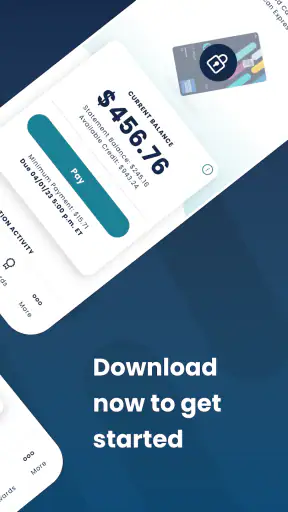
A realistic first-week scenario would be a cardholder preparing for a larger household purchase. Before buying, I would open the app to review the account, confirm the available information shown there, and check whether rewards are ready to use. Afterward, I could return to make a payment without switching to a desktop browser. That is not a dramatic transformation, but it removes enough friction to make responsible account checking more likely.
There is also a practical advantage in building a habit around one trusted place. If you tend to postpone financial administration because it feels inconvenient, a mobile app can turn a vague intention into a short routine. I would not call this a budgeting system, though. The experience is centered on the Bread Financial relationship, so anyone expecting a complete picture of several banks, cards, bills, and investments will need additional tools.
The current release is version 5.8.2 and requires iOS or Android 11 or later. That requirement is reasonable for people using a relatively recent device, but it is worth checking before planning to install it on an older phone. The app is free, which removes a direct cost barrier, although normal account terms and any financial consequences connected to payments remain separate from the app itself.
The small workflow improvements that matter
One useful habit is to treat the app as a checkpoint rather than an emergency tool. Checking the account briefly at a regular time can help you notice activity, upcoming payment needs, or available rewards before they become urgent. I find this more sustainable than opening a finance app only after receiving a reminder or realizing that a statement has been ignored.
A second insight is that rewards should be checked at the same time as payment planning. People often think of rewards as a bonus and payments as a responsibility, but combining the two screens in one routine makes the account easier to understand as a whole. Before redeeming anything, I would consider whether using the reward now is genuinely useful or whether keeping it available better matches my plans.
A third trade-off is the value of specialization. A narrow app can be faster for its intended account than a general-purpose banking app, but it will not give you the broader context that helps with household budgeting. I would use Bread Financial for account-specific actions and another tool for comparing total spending across providers. Trying to force it into both roles would create unnecessary frustration.
Why it can keep earning a place month after month
Long-term value in this app depends on repetition. Payment management is not a one-time feature; it is a recurring need. If you use a Bread Financial account regularly, the ability to handle that task from a phone gives the app a reason to stay installed. The same is true for rewards, but only when you remember to inspect them and they remain relevant to how you spend.
I see the strongest recurring use case in a simple monthly cycle. First, review the account after the statement or spending period. Next, decide what payment action makes sense for your situation. Finally, check rewards while the account is already open. This sequence is more useful than opening the app randomly, because every visit has a clear purpose and the three tasks reinforce one another.
The app is also helpful for people who dislike relying on a browser for financial administration. Mobile access does not automatically make a payment safer or wiser, but it can make the process easier to complete on time. That distinction matters. Convenience supports a good habit, yet it cannot substitute for reading account details carefully or choosing a payment amount responsibly.
For someone with a single Bread Financial account, this focused design may be enough. The app’s value becomes less clear for a person who wants consolidated finances. A broad banking application may be better if you need one place to compare multiple institutions, track categories, monitor cash flow, and see every obligation together. Bread Financial is more like a dedicated control panel than a complete financial command center.
I would also avoid judging its usefulness solely by how often it is opened. A finance app can earn its space through occasional, important actions. If it lets you complete a payment or redeem a reward when you need to, that may justify keeping it even if you do not use it every day. The better question is whether those actions are easier and more reliable for you in the app than through the usual browser alternative.
The audience size and strong average rating make the app easier to take seriously, but they do not remove the need for personal testing. Different users have different expectations about speed, account detail, alerts, and organization. I would give it a fair trial through one complete payment cycle rather than deciding after a single launch. That reveals whether the app fits your real routine instead of merely looking convenient at first.
Where the monthly routine can become tiring
The main source of fatigue is repetition without expansion. Once you have learned where to manage the account, the experience may feel familiar rather than rewarding. That is acceptable for a utility, but it means the app needs to remain dependable and easy to revisit. If your account activity is low or you rarely use rewards, you may not feel a strong reason to open it between statements.
Another potential frustration is expecting broader financial insight from a specialized account app. If you want detailed spending analysis across different cards, a household budget, or a unified view of recurring bills, this is not the tool I would choose as the center of that system. Adding those expectations can make a perfectly serviceable account app seem incomplete when its purpose is narrower.
There is also a behavioral risk in making payments feel too effortless. A short mobile workflow is convenient, but convenience can encourage rushed decisions. I would still pause to review the account information and confirm the payment action before submitting it. The best routine is quick because it is organized, not because it skips attention.
Rewards can create a similar distraction. Seeing them regularly may encourage useful redemption, but it can also tempt you to treat rewards as a reason to spend more. I would use the app to understand what is available, not to justify purchases that would otherwise be unnecessary. That is an important long-term boundary for any rewards-linked finance product.
Maintenance is relatively simple from a user’s perspective: keep the app updated, protect access to the phone and account, and review information rather than assuming that every visit requires an action. The current version, 5.8.2, indicates an actively maintained release line, but I would still pay attention to how well the app behaves on your device and whether it remains compatible with your operating system.
Because the minimum operating-system requirement is Android or iOS 11, people using older hardware may face the first practical barrier before they can evaluate the experience. For supported phones, installation is straightforward because the app costs nothing. For unsupported devices, the browser may remain the more realistic route, assuming the account can be managed there.
Who should use it and who should skip it
I would recommend Bread Financial to someone who actively manages a Bread Financial account and wants a direct mobile route for payments and rewards. It is especially suitable for people who prefer short, repeatable routines over a feature-heavy financial dashboard. If you often travel, work away from home, or simply handle administration from your phone, that convenience can be meaningful.
I would also recommend trying it if you repeatedly forget to check rewards. Bringing account management and redemption into the same habit gives those benefits a better chance of being noticed. The app is most useful when it becomes part of a monthly review, not when it is installed and then left untouched.
I would skip it as a primary finance app if your needs begin with aggregation. Someone managing several cards, bank accounts, investments, and shared household expenses will probably be better served by a broader banking or budgeting solution. You could still keep this app for Bread Financial-specific tasks, but it should not be expected to replace the larger system.
I would also hesitate if you rarely use the associated account and do not care about mobile access. In that case, the app may add another login and another notification source without delivering enough recurring value. A dedicated app earns its place when it removes a task you actually perform, not simply because it exists.
My long-term verdict on Bread Financial
After the first-week convenience fades, the app’s case rests on maintenance rather than novelty. It does not need to entertain me or constantly introduce new reasons to return. It needs to make account review, payment management, and rewards redemption clear enough that I am willing to repeat them. On that narrower test, it makes sense for the right user.
My final judgment is positive but deliberately limited: Bread Financial is worth keeping when it supports an account you actively use. Its free access and focused purpose lower the barrier to trying it, while the strong user response suggests that many people find the core experience useful. Still, I would not install it expecting a full budgeting platform or a unified view of every financial relationship.
The best way to decide is to test one complete routine. Open the account, review what matters, make the payment action you need, and inspect the rewards area without rushing to redeem. Then repeat that process during the next regular account cycle. If the app makes those steps easier than your browser and helps you remember them, it has earned permanent space. If it merely duplicates a process you already handle comfortably elsewhere, removing it is reasonable.
In my experience, that is the honest appeal here. Bread Financial is not a spectacular all-purpose finance solution, and it does not need to be. It is a practical companion for a specific account relationship. Its lasting value comes from dependable repetition: a quick check, a considered payment, and a timely look at rewards. For that job, I would recommend giving it a place on your phone, while keeping your broader financial planning in a tool designed for the bigger picture.


